At a glance
A one-participant plan is a retirement plan, other than an ESOP, that covers only the owner (or the owner and spouse) of a wholly owned business, or only partners and their spouses, with a 2% S corporation shareholder treated as a partner. Such a plan, or a foreign plan, “cannot file an annual return on Form 5500, Annual Return/Report of Employee Benefit Plan, or Form 5500-SF”. See one-participant plans for the eligibility details.
| Question | Answer for the 2025 Form 5500-EZ |
|---|---|
| Who files | One-participant plans and foreign plans that must file under Code section 6058(a) |
| Who does not | A one-participant plan when the total of its assets and those of the employer's other one-participant plans at year end “does not exceed $250,000, unless 2025 is the final plan year of the plan” |
| Due date | Last day of the 7th calendar month after the plan year ends; see Form 5500 due date |
| Extension | Form 5558 (up to 2½ months) or the automatic extension tied to the employer's tax return |
| Schedules | None filed. Keep a completed Schedule MB and a completed and signed Schedule SB if applicable |
| Public? | Available to the public, but “will not be published on the internet” |
| Penalty | “Section 6652(e) imposes a penalty of $250 a day (up to a maximum penalty of $150,000 per plan year)”; see penalties |
The $250,000 test counts every one-participant plan the employer maintains. If the combined total exceeds $250,000 at the end of the 2025 plan year, a Form 5500-EZ is due for each of those plans, including one with less than $250,000 on its own.
Paper or EFAST2
Since plan years beginning after 2019 the EZ can be filed electronically through EFAST2, by IFILE or approved software. Paper is still allowed for most filers: the official IRS printed form, the fillable form on IRS.gov printed and signed, or approved software, mailed to the Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0020. Two rules override the choice:
- Mandatory electronic filing: for plan years beginning on or after January 1, 2025, you must use EFAST2 “if the filer is required to file at least 10 returns of any type with the IRS”, counting W-2s, 1099s and tax returns, during the calendar year that includes the first day of the plan year. If you must file electronically and file on paper instead, “the filer is considered to have not filed the form even if a paper Form 5500-EZ is submitted”. The IRS may waive the requirement for undue economic hardship.
- Late filer relief: a delinquent return under the IRS Late Filer Penalty Relief Program (Rev. Proc. 2015-32) must be on paper, with box D checked.
The DOL's late filer program (DFVCP) lists Form 5500-EZ filers and one-participant plans as not eligible. The IRS calls these non-Title I plans, so the IRS program is the route.
The form, line by line
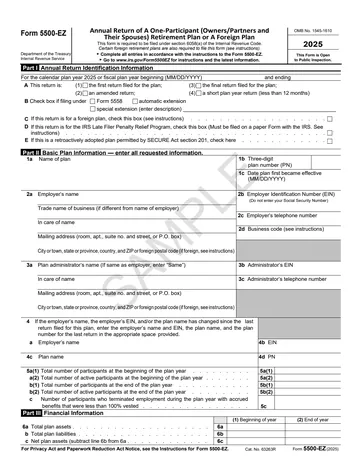
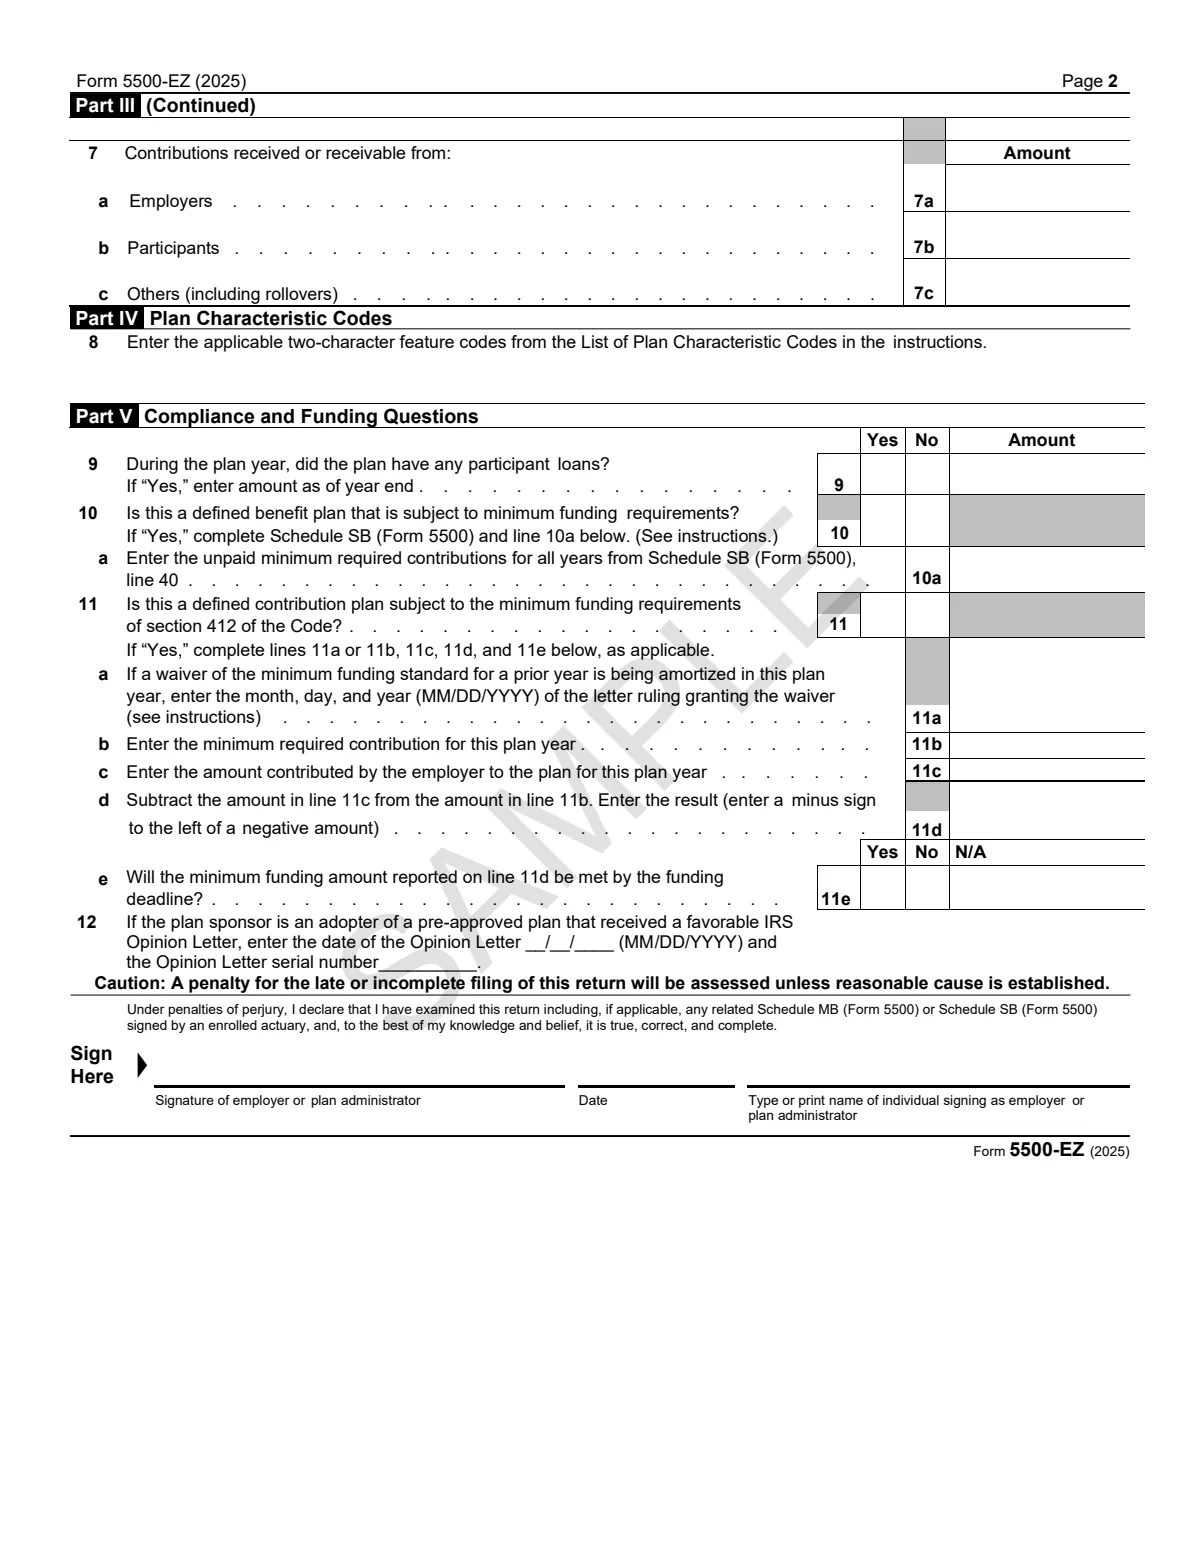
Hover or tap any box to see what goes there; click it to jump to the full note. Use the page buttons for page 2.
Swipe sideways to see the whole page, or pinch to zoom. Tap a box once for its note, again to jump to the line.
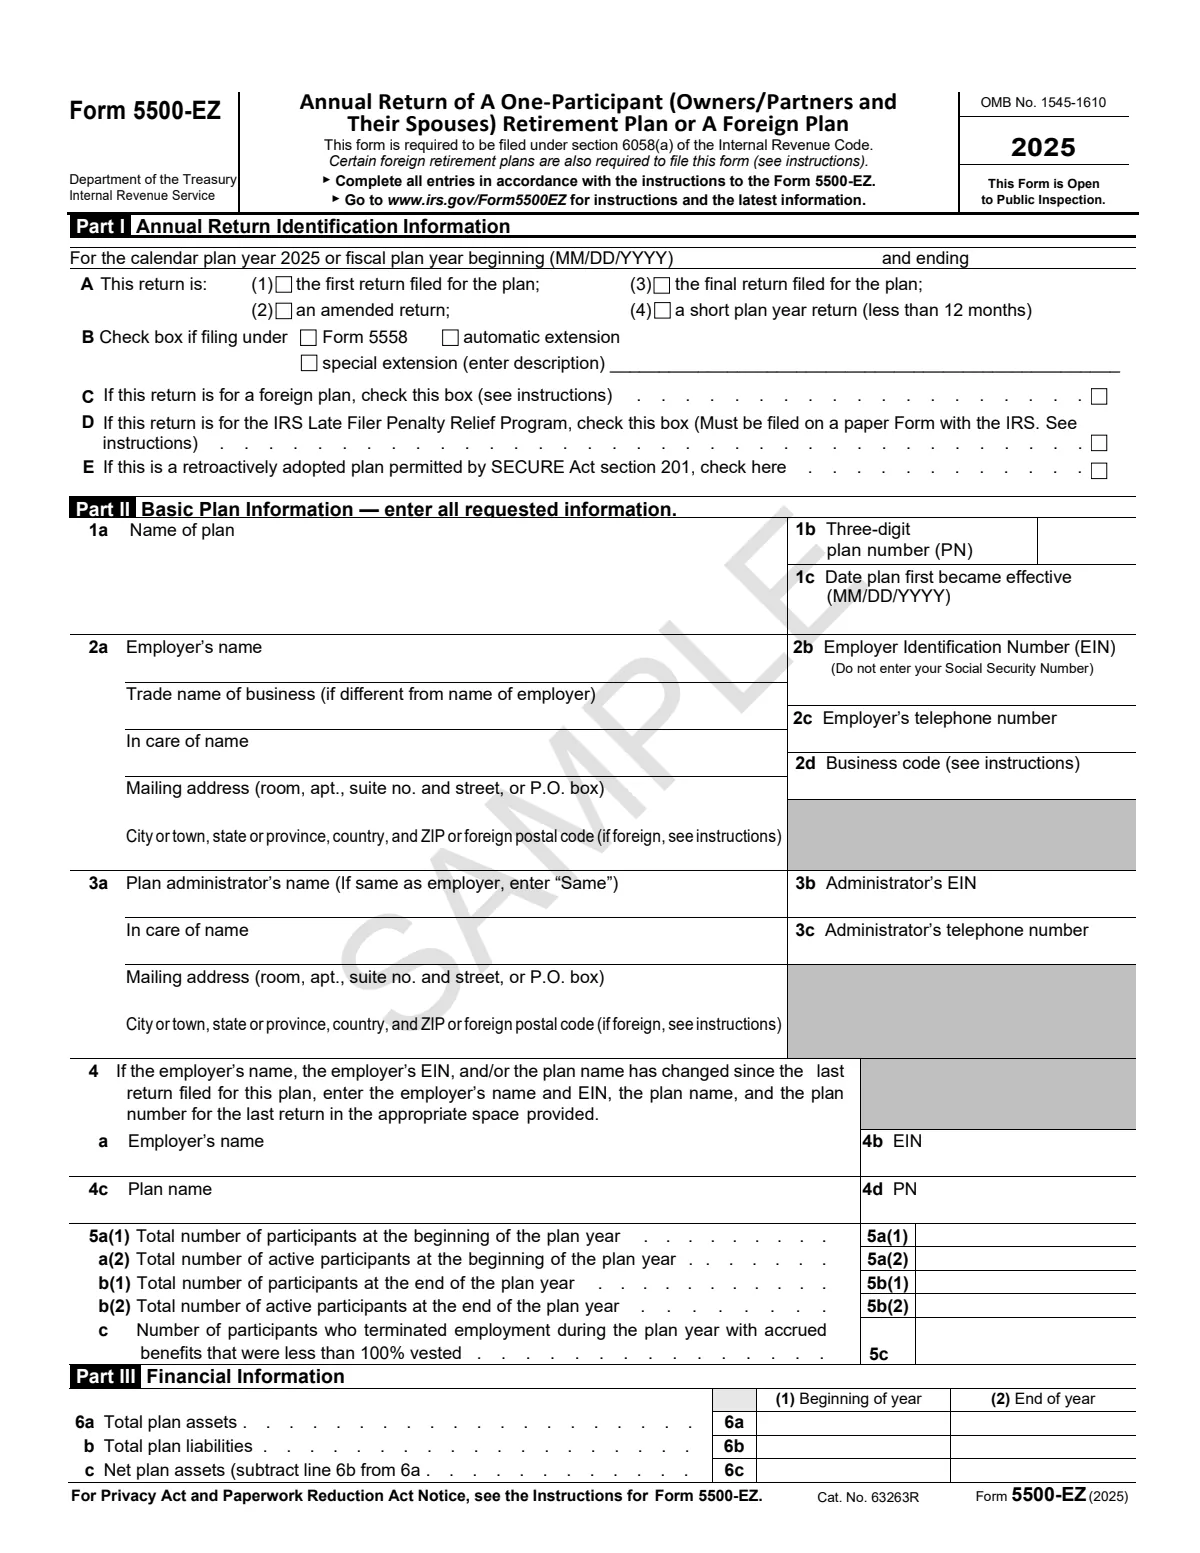
Part I: identification
| Line | Label | What goes there |
|---|---|---|
| Year | Plan year beginning and ending | Enter the calendar or fiscal year beginning and ending dates of the plan year (not more than 12 months) in MM/DD/YYYY order. For a short plan year, enter the short year's dates. The short year ends on the date of the change in accounting period or the complete distribution of the plan's assets. |
| A | This return is | A(1): only if nothing was ever filed for this plan on any form, including a Form 5500. A(2): an amended 2025 return. Amend electronically if the original was filed electronically and on paper if it was filed on paper. “Do Not use Form 5500-SF for an amended return of a one-participant plan or a foreign plan”. A(3): all assets distributed or transferred; the final plan year is the year distribution is completed. A(4): a period of less than 12 months. |
| B | Check box if filing under | Form 5558: up to 2½ months if filed by the normal due date; do not attach it (see Form 5558). Automatic extension: the plan year and the employer's tax year match and the employer has an income tax extension; no Form 5558 is needed, and it cannot be extended further by a Form 5558 filed after the normal due date. Special extension: an IRS-announced extension, such as disaster relief, with a description. |
| C | Foreign plan | A foreign plan files if the employer is a domestic employer, or a foreign employer with U.S. source income that deducts plan contributions on its U.S. income tax return. A qualified foreign plan under Code section 404A(e) that does not qualify for section 402(d) treatment does not file. |
| D | IRS Late Filer Penalty Relief Program | Rev. Proc. 2015-32 gives one-participant and foreign plans relief from the Code section 6652(e) and 6692 penalties for late returns. “The delinquent return cannot be filed electronically through the EFAST2 System.” With box D checked, the 2025 return need not carry the red-letter legend, but each submission needs Form 14704 attached to the front of the oldest delinquent return. |
| E | Retroactively adopted plan (SECURE Act section 201) | No 2024 Form 5500-EZ is required. A defined benefit plan's actuary completes and signs both the 2024 and 2025 Schedules SB, and the sponsor keeps both. |
Part II: basic plan information
Participant counts on line 5 use the same categories as the Form 5500: active, retired or separated, and deceased participants with beneficiaries.
| Line | Label | What goes there |
|---|---|---|
| 1a | Name of plan | Enter the formal name of the plan. EFAST2 compares line 1a with last year's plan name (warning Z-003). |
| 1b | Three-digit plan number (PN) | Number plans consecutively from 001. Once used, the number stays with the plan and is never used for another plan, even after termination. |
| 1c | Date plan first became effective | Enter the date the plan first became effective. |
| 2a | Employer's name and address | A post office box is allowed only if the Post Office does not deliver to the street address. For a foreign address, enter city, province, country and postal code in that order and do not abbreviate the country. Use Form 8822-B for an address or responsible party change. |
| 2b | Employer Identification Number (EIN) | Enter the employer's EIN, for example 00-1234567, never an SSN. An employer without an EIN applies online at IRS.gov or with Form SS-4; foreign plans cannot apply online and may call 267-941-1099. |
| 2c | Employer's telephone number | Enter the employer's telephone number including the area code. |
| 2d | Business code | Use the code from the list at the end of the 2025 instructions that best describes the plan sponsor's business. |
| 3a | Plan administrator's name and address | Otherwise enter the administrator's name, any in care of name, street address, and city, state and ZIP, one per row. |
| 3b | Administrator's EIN | A plan administrator must have an EIN for Form 5500-EZ reporting. |
| 3c | Administrator's telephone number | Enter the administrator's telephone number including the area code. |
| 4 | Change in employer name, EIN or plan name (4a to 4d) | Enter the employer's name (4a) and EIN (4b), the plan name (4c) and the plan number (4d) as they appeared on the last return filed for the plan. |
| 5a(1) | Total participants at the beginning of the plan year | A participant is an active participant, a retired or separated participant receiving or entitled to benefits, or a deceased participant with a beneficiary entitled to benefits. |
| 5a(2) | Active participants at the beginning of the plan year | Count participants currently in covered employment and earning or retaining credited service. |
| 5b(1) | Total participants at the end of the plan year | Same categories as 5a(1), counted at year end. |
| 5b(2) | Active participants at the end of the plan year | Same definition as 5a(2), counted at year end. |
| 5c | Participants who terminated with less than 100% vesting | Include each individual who terminated employment during the year with accrued benefits less than 100% vested, whether or not they had a break in service or received a cash or deemed distribution. |
Parts III and IV: financial information and codes
Use the cash, modified cash or accrual basis consistently, and whole dollars only.
| Line | Label | What goes there |
|---|---|---|
| 6a | Total plan assets | Total plan assets include rollovers and transfers received, unrealized gains and losses, and specific assets such as partnership interests, real estate, employer securities, loans and tangible property. Leave 2025 contributions out of column (1). “You should use the total plan assets as listed as of the end of the plan year on line 6a(2) of this form to determine whether the plan(s) assets exceed $250,000.” Use whole dollars, and match last year's end of year amounts. |
| 6b | Total plan liabilities | Liabilities do not include the value of future distributions to participants. |
| 6c | Net plan assets (6a minus 6b) | Subtract line 6b from line 6a, beginning and end of year. |
| 7a | Contributions from employers | Enter the total cash contributions received and/or receivable from employers during the plan year. |
| 7b | Contributions from participants | Enter the total cash contributions received and/or receivable from participants during the plan year. |
| 7c | Other contributions (including rollovers) | Enter all other contributions, including transfers or rollovers received from other plans, valued on the date of contribution. |
| 8 | Plan characteristic codes | Use only the EZ instructions' list: defined benefit codes 1A to 1I (1G is new for 2025), defined contribution codes such as 2E profit-sharing, 2J 401(k) feature and 2C money purchase, and other codes such as 3A non-U.S. plan, 3B self-employed individuals, 3D pre-approved plan and 3E for a plan that meets coverage only when combined with another plan. An eligible combined plan enters codes for both parts. |
Part V: compliance and funding
Lines 10 and 11 apply only to plans subject to minimum funding: defined benefit plans (line 10) and money purchase or target benefit plans (line 11). Even though Schedules SB and MB are not filed with the EZ, the plan must still perform an annual valuation and keep the funding records as if they were filed. The 2025 Schedules MB and SB are available electronically from EFAST2 for your records; do not try to file them with the EZ.
| Line | Label | What goes there |
|---|---|---|
| 9 | Participant loans | Include all participant loans, including residential loans subject to Code section 72(p). “Do not include a participant loan that has been deemed distributed.” |
| 10 | Defined benefit plan subject to minimum funding? | Check Yes if the plan is a defined benefit plan subject to the minimum funding standard of Code section 412. |
| 10a | Unpaid minimum required contributions | If the plan is a defined benefit plan, “the enrolled actuary must complete and sign the 2025 Schedule SB (Form 5500)” and forward it by the filing due date to the person filing the EZ. The Schedule SB is kept under the Code's records rules. See Schedule SB. |
| 11 | Defined contribution plan subject to minimum funding? | If Yes, the form directs you to complete line 11a, or lines 11b, 11c, 11d and 11e, as applicable. |
| 11a | Funding waiver letter ruling date | A money purchase plan amortizing a waiver completes lines 3, 9 and 10 of Schedule MB. Do not attach Schedule MB; keep it with the plan's records. |
| 11b | Minimum required contribution | Enter the minimum required contribution for this plan year. |
| 11c | Employer contributions for the plan year | Enter the amount contributed by the employer to the plan for this plan year. |
| 11d | Line 11b minus line 11c | The form's instruction: “Subtract the amount in line 11c from the amount in line 11b.” Enter a minus sign to the left of a negative amount. |
| 11e | Will the minimum funding amount be met by the funding deadline? | Check Yes, No or N/A. An accumulated funding deficiency is subject to an excise tax reported on Form 5330. |
| 12 | Pre-approved plan opinion letter | The serial number is a capital letter followed by six numbers. A plan modified in a way that negates the opinion letter is treated as an individually designed plan. |
Signature
| Line | Label | What goes there |
|---|---|---|
| Sig | Signature of employer or plan administrator | “The plan administrator or employer (owner) must sign and date paper Form 5500-EZ for the 2025 filing.” For an electronic filing, the signer registers in EFAST2 as a Filing Signer, which covers the 5500-EZ, and signs with a User ID and PIN. |
Common mistakes
| Mistake | Fix |
|---|---|
| Testing $250,000 plan by plan | Add the year end assets of every one-participant plan the employer maintains |
| Skipping the final year return because assets are under $250,000 | A final return is due for the final plan year whatever the balance |
| Filing a Form 5500 or 5500-SF for a one-participant plan (EFAST2 I-207) | File the 5500-EZ; it is not posted on the internet |
| Filing on paper when 10 or more IRS returns were required in the calendar year | File through EFAST2, or the return is treated as not filed |
| Submitting a late filer program return through EFAST2 | Late filer relief returns go on paper to the IRS with box D checked |
| Checking the first return box after earlier filings on another form | A(1) is only for a plan that has never filed |
| Leaving line 8 blank | Enter every applicable code from the EZ list in the 2025 instructions |
Once the plan provides benefits for anyone other than the owner, the partners or their spouses, it is no longer a one-participant plan. It then files the Form 5500 or, if eligible, the Form 5500-SF electronically.
Questions filers ask
Do I have to file Form 5500-EZ for my solo 401(k)?
Only if the year end assets of all the employer's one-participant plans together exceed $250,000, or if 2025 is the plan's final year. Below that, no return is due for the year.
Can I still file the 5500-EZ on paper?
Yes, unless you were required to file at least 10 returns of any type with the IRS during the calendar year that includes the first day of the plan year. Then you must file through EFAST2.
Is the 5500-EZ public?
The information must be made available to the public, but the IRS instructions say it will not be published on the internet, whether filed on paper or through EFAST2.
Do I attach Schedule SB for a one-participant defined benefit plan?
No. No schedules are filed with the EZ. The enrolled actuary still completes and signs Schedule SB, and you keep it with the plan's records and report its line 40 amount on line 10a.
I missed several years. Can I use EFAST2 to catch up?
Not under the IRS Late Filer Penalty Relief Program: those delinquent returns must be filed on paper, with box D checked on the 2025 form and Form 14704 attached to the oldest return.