At a glance
“Use Form 5558 to apply for a one-time extension of time to file the Form 5500 series, and Form 8955-SSA.” The Form 5500 instructions put it the same way: “A plan, GIA, or DCG may obtain a one-time extension of time to file a Form 5500 Annual Return/Report (up to 2½ months)” by filing Form 5558 on or before the normal due date. For the deeper deadline rules, see Form 5558: extending the Form 5500 deadline.
| Question | Answer from the form and instructions |
|---|---|
| Who files | The plan sponsor or plan administrator, the same one named on the plan's annual return/report. A DCG's plan administrator can file one Form 5558 for the whole arrangement. |
| Who signs | No one. The IFILE guide says “There is no signature for Form 5558.” The IRS says “Signatures are not needed for extension of time to file Form 5500 series or Form 8955-SSA.” |
| Returns it extends | Form 5500, 5500-SF, 5500-EZ and 8955-SSA |
| How long | To no later than the 15th day of the 3rd month after the normal due date (2½ months) |
| When to file | On or before the normal due date of the return being extended |
| How to file | Electronically through EFAST2 (IFILE or approved third-party software) since January 1, 2025, or on paper with the IRS in Ogden, Utah |
| One plan per form | “A separate Form 5558 must be used for each plan for which an extension is requested.” |
A DCG is the one exception to one plan per form: the single Form 5558 filed by the DCG covers every plan participating in the arrangement. No list of participating plans is attached.
The form, line by line
Form 5558 is a single page; pages 2 and 3 of the PDF are the instructions. Hover over or tap a box for the rule, and click to jump to the full note.
Swipe sideways to see the whole page, or pinch to zoom. Tap a box once for its note, again to jump to the line.
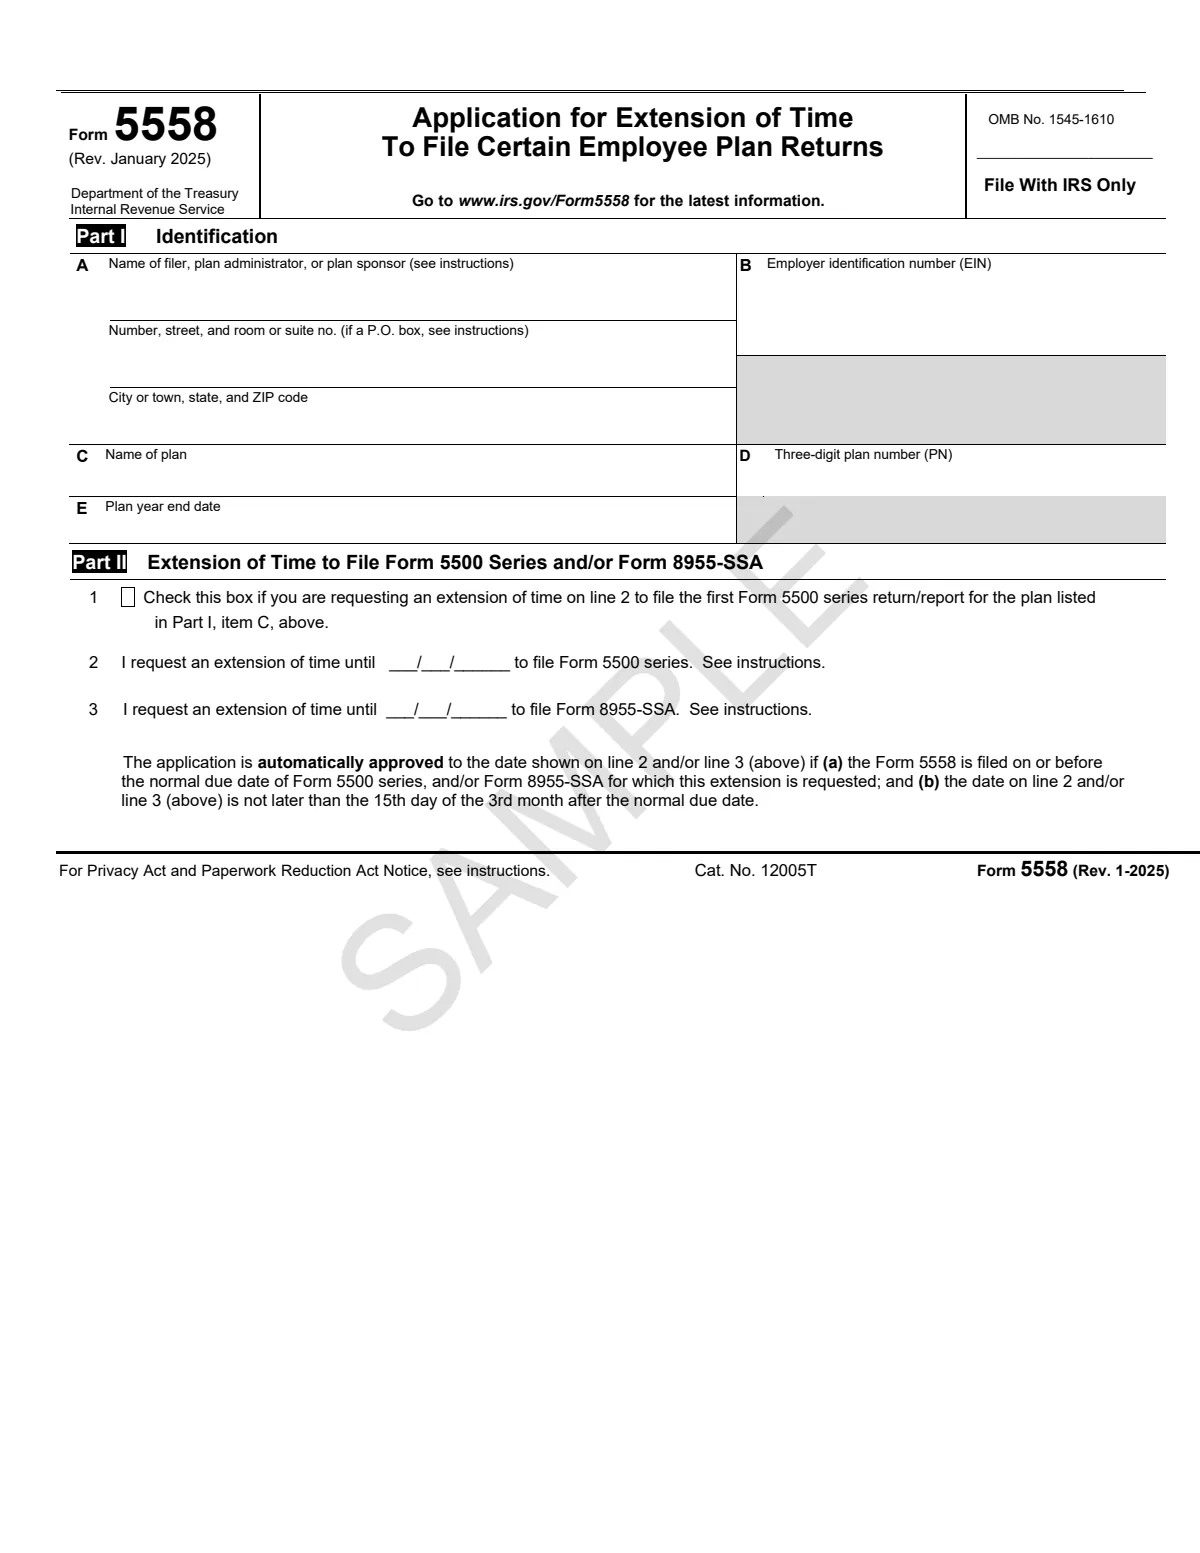
| Line | Label | What goes there |
|---|---|---|
| Header | Form 5558 (Rev. January 2025), File With IRS Only | Filers must use the current revision: the instructions require the most recent version of the form. The legend is from the paper form; the instructions now say “Beginning January 1, 2025, Form 5558 can be filed electronically through EFAST2 or can be filed with the IRS on paper.” |
| A | Name of filer, plan administrator, or plan sponsor | “The plan sponsor (generally, the employer for a single-employer plan) or plan administrator listed on the application should be the same as the plan sponsor or plan administrator listed on the annual return/report filed for the plan.” For a one-participant plan, the Form 5500-EZ instructions note the plan sponsor name is generally the same as the employer name. |
| A-addr | Number, street, room or suite; city or town, state and ZIP code | Put the suite or room after the street address. Use a P.O. box only if mail is not delivered to the street. Foreign addresses: city, province or state, and country, with the country's postal code, and the country name not abbreviated. A new address on Form 5558 does not update IRS records; use Form 8822-B for that. |
| B | Employer identification number (EIN) | Enter the nine-digit EIN assigned to the employer, in XX-XXXXXXX format. An entity without an EIN applies online at irs.gov/EIN, or by fax or mail on Form SS-4. Do not use a Social Security number. |
| C | Name of plan | Enter the formal name of the plan. |
| D | Three-digit plan number (PN) | The PN is required. Plans are numbered consecutively starting with 001. Once a PN is used for a plan, it stays with that plan for all future returns, and it may not be reused for another plan even after the first plan ends. |
| E | Plan year end date | Enter the plan year ending date as MM/DD/YYYY. The plan year is the calendar or fiscal year for which the plan's records are kept. |
| 1 | First Form 5500 series return | Check the box if the extension on line 2 is for the first Form 5500 series return/report for the plan. Leave it blank if the plan has ever filed a Form 5500 series return for any year. |
| 2 | I request an extension of time until ___ to file Form 5500 series | Enter the date you are requesting for the Form 5500, 5500-SF or 5500-EZ. It should be no later than the 15th day of the 3rd month after the normal due date. |
| 3 | I request an extension of time until ___ to file Form 8955-SSA | Same rule for Form 8955-SSA. A single Form 5558 may extend both the plan's Form 5500 series return and its Form 8955-SSA. See Form 8955-SSA. |
| Approval | Automatic approval statement | Applications filed on time on a properly completed Form 5558 “will be automatically approved to the date that is no later than the 15th day of the 3rd month after the return/report’s normal due date”. The IRS does not return approved copies, so keep your own. |
Extended due dates
The normal due date of a Form 5500 series return is the last day of the 7th month after the plan year ends, and Form 8955-SSA has the same deadline. Form 5558 moves both to the 15th day of the 3rd month after that date. The table applies the rule before any weekend or holiday shift; if the date falls on a Saturday, Sunday or legal holiday, the return may be filed on the next day that is not one.
| Plan year ends | Normal due date | Latest date on line 2 or 3 | Form 5558 due by |
|---|---|---|---|
| December 31 | July 31 | October 15 | July 31 |
| March 31 | October 31 | January 15 | October 31 |
| June 30 | January 31 | April 15 | January 31 |
| September 30 | April 30 | July 15 | April 30 |
For any plan year end, the Form 5500 due date calculator works out both dates. When the Form 5500 is filed, check the Form 5558 extension box: line D on the Form 5500, line C on the 5500-SF, Part I line B on the 5500-EZ, and Part I line C on Form 8955-SSA. Do not attach the Form 5558: “Filers are not required to attach a copy of the submitted IRS Form 5558 with their completed Form 5500.” Keep a copy in the plan's records.
Filing through EFAST2
“Effective January 1, 2025, filers can submit Form 5558 electronically through EFAST2 using IFILE on the EFAST2 website or third-party software.” The IFILE steps:
- On the Filing Summary page, click Create a Filing. If the option is missing, add Filing Author as a user type in your EFAST2 profile.
- Choose the Form 5558 option on the Form Selection page and click Create.
- Enter the form in one sitting. There is no save option, and 15 minutes of inactivity logs you out and loses the data.
- Click Validate and fix any errors or warnings.
- Click View PDF and save a copy for your records. After submission the form cannot be viewed, saved or printed.
- Click Submit, then Submit again on the confirmation message. A success window confirms receipt.
What EFAST2 does not give you for a Form 5558:
| Feature | Form 5558 in EFAST2 |
|---|---|
| Acknowledgment ID | “There is no Acknowledgment ID (AckID) for a submitted Form 5558.” |
| Amendments | Not possible: a Form 5558 cannot be amended. |
| Email receipt | No system-generated email acknowledges receipt. |
| Status check | Not available on the EFAST2 website, by the EFAST2 Contact Center, or through third-party software. Call the IRS at 877-829-5500. |
| Signature | Not required. |
| Batches | A batch can hold Form 5500 series filings or Forms 5558, not both. |
See how to file in EFAST2 for EFAST2 accounts and user types.
Filing on paper
Paper filers mail the current form to the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0045. Certain IRS-designated private delivery services can be used to meet the timely mailing as timely filing rule, but they cannot deliver to a P.O. box; the instructions point to irs.gov/PDS for the list and street addresses.
What Form 5558 does not do
- It does not extend the PBGC premium. The extension “does not operate as an extension of time to file the PBGC (Pension Benefit Guaranty Corporation) Form 1, Annual Premium Payment”.
- It does not extend Form 5330. “Form 5558 is no longer used to apply for an extension of time to file Form 5330”; use Form 8868. See Form 5330.
- It does not stack on the automatic extension. An extension based on the employer's tax return extension cannot be pushed further with a Form 5558 filed after the normal due date.
- It does not change when penalties start if you miss the extended date. The DOL says “If you received an extension, but the filing is submitted to EFAST after the extension period, penalties are calculated from the original due date.” See Form 5500 penalties.
- It is not a filing. “Delinquency notices are based on when the Form 5500 is filed, not the filing of the Form 5558.”
- It does not cover other plans. Lists of other plans attached to the form are not processed.
The automatic extension instead
A plan does not need Form 5558 if both conditions in the instructions are met: the plan year and the employer's tax year are the same, and the employer has an extension to file its federal income tax return to a date later than the normal Form 5500 due date. The Form 5500 instructions add a third condition: a copy of the employer's extension application is kept with the filer's records. That extension cannot be extended further with Form 5558, and cannot run past 9½ months after the plan year closes. Check the automatic extension box on the Form 5500, not the Form 5558 box.
Common mistakes
- Filing on or after the original due date has passed. The form must be filed on or before the normal due date, without extensions.
- Using an old revision. The January 2025 revision must be used instead of the January 2024 version or any earlier one.
- One form for several plans. Each plan needs its own Form 5558, except a DCG.
- A name that does not match the return. Use the same plan sponsor or administrator as on the Form 5500 series return.
- A wrong or missing PN. The PN is required and must be the plan's permanent number.
- Checking line 1 for a plan that filed before. Line 1 is only for the plan's first Form 5500 series return.
- Not saving a copy in IFILE. After submission the form cannot be viewed or printed, and no approved copy is mailed back.
Questions filers ask
Does Form 5558 need a signature?
No. The IFILE guide says there is no signature for Form 5558, the EFAST2 guide says it does not require an electronic signature, and the IRS says signatures are not needed for extensions of Form 5500 series or 8955-SSA returns.
How do I know the IRS received my Form 5558?
EFAST2 shows a success window after submission but gives no AckID, no email and no status lookup. For questions about receipt, the EFAST2 guide says to call the IRS at 877-829-5500. Keep your saved PDF.
Can I file Form 5558 after July 31 for a calendar year plan?
No. It must be filed on or before the normal due date of the return. After that date, the options are filing the Form 5500 late and, for the DOL, the DFVCP.
Can one Form 5558 extend the Form 5500 and Form 8955-SSA?
Yes, for the same plan. Fill in both line 2 and line 3.
Do I attach Form 5558 to the Form 5500?
No. Check the Form 5558 extension box on the return and keep a copy of the Form 5558 with the plan's records.
Does Form 5558 extend the PBGC premium filing?
No. The instructions say it does not extend the time to file PBGC Form 1, Annual Premium Payment.